Hong Kong’s Gold Clearing and Title to Specific Gold Bars
Hong Kong is building itself into a gold hub, and in July 2026 it began trialling the piece the market had lacked: a clearing system of its own. Until then, a gold deal between two banks in the city settled directly between them or through accounts in London. Participating banks now settle on one central ledger run by the wholly government-owned Hong Kong Precious Metals Central Clearing Company (HKPMCC), against metal that stays in the city: 400 oz bars deposited at Bank of China (Hong Kong), the system’s designated vault. When gold changes hands, the ledger moves a balance from one bank to another; the bars stay in the vault, held together, with none assigned to any one bank.
For a company or family office that holds gold through one of those banks, the system changes how the bank settles. The client’s own position stays where it was, in its agreement with the bank. Title to specific bars is a different arrangement: particular bars, listed by serial number, refiner, weight and fineness, kept apart from everyone else’s metal and released on the owner’s instruction. On a summary report both read as gold held in Hong Kong, and they part ways the day a board or an auditor asks to see the bars.
Hong Kong’s gold central clearing and settlement system
On 7 July 2026 the system went into trial operation, with the first gold deposited into the vault and deals cleared and settled the same day. It is run by HKPMCC, which the government set up in January 2026 and owns outright. Eleven banks sit on the company’s board alongside the government, the Shanghai Gold Exchange and the city’s regulators. They range from global banks such as HSBC, JPMorgan, UBS, Citi and Standard Chartered to the Hong Kong arms of the large mainland lenders. The system adds a central settlement layer to a market that already ran an exchange, vaults and two LBMA refineries.
The Clearing Rulebook fixes the rights, obligations and procedures of every participating bank and of the designated vault. Alongside it runs a central ledger that records every settlement, every transfer of gold and the balance of each participating bank. The ledger is wired to the vault, so metal is recorded as it comes in and goes out. Bank of China (Hong Kong) serves as both settlement institution and designated vault, under HKPMCC’s oversight, and the gold it holds for the system is the 400 oz bar of international standard.
Banks are the participants that hold balances in the ledger. Everyone else reaches the system through a bank: the first settlements involved banks together with their clients, among them mining companies, refiners, jewellers and other investors.
For now the system runs as a trial, on real deposits and real settlements. HKPMCC is identifying improvements to make before formal commissioning, which is scheduled for the first quarter of 2027. Bryan Chan, a former executive of Hong Kong Exchanges and Clearing, became its first chief executive on 2 October. The system is also due to connect to Hong Kong’s Real Time Gross Settlement system, so that gold and the cash paid for it settle together, delivery versus payment.
How positions are held inside the system
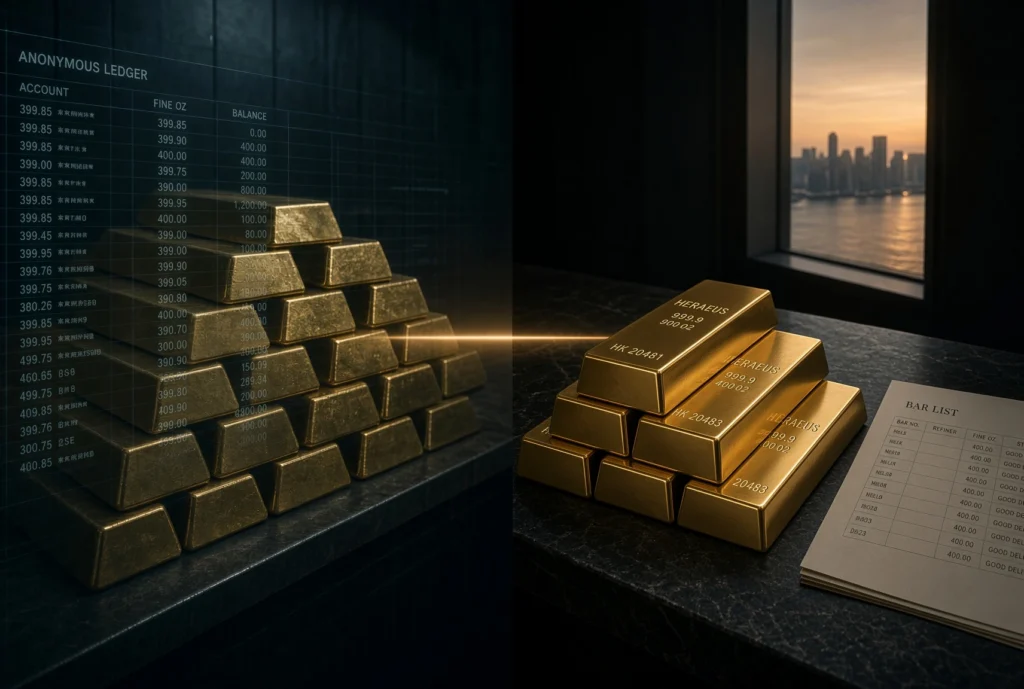
Inside the system, gold is held and settled on an unallocated basis. The bars in the vault form one commingled stock, and each participating bank’s balance is a quantity of gold measured against that stock, with no particular bar assigned to it. When one bank sells to another, nothing moves in the vault: the ledger takes the gold off one balance and adds it to the other. Bars move when a bank deposits metal into the vault or takes it out.
Commingling is what lets the system settle quickly and in volume. A deal becomes a ledger entry, and no 12 kg bar has to travel for it. Wholesale gold has cleared this way in London for decades, and Hong Kong built its system on the same logic.
For a company holding gold through a participating bank, the position runs through three layers:
- Bank of China (Hong Kong) holds the bars, as one stock.
- The ledger records the bank’s balance against that stock, with the bank’s rights set by the Clearing Rulebook.
- The bank records the client’s position, on the terms of the client’s agreement with the bank.
The ledger and the Rulebook govern the first two layers. The third belongs to the client’s contract with its bank, and that contract decides what the client holds: gold in an account measured in ounces, or specific bars the bank keeps for the client. The difference between allocated and unallocated gold turns on exactly that point.
One bar format, two kinds of record
Ahead of the launch, at least four participating banks shipped 400 oz bars into the city to build stock for physical delivery, lifting Hong Kong’s gold imports above their two-year average. The system settles in 400 oz bars, the institutional standard of the London wholesale market, while Hong Kong’s local market, like Shanghai and Singapore, trades mainly in kilobars.
Central banks hold this bar in their reserves. Weights vary from bar to bar, so each one carries a serial number, refiner’s mark and fineness, with its fine weight recorded individually. Where the bar goes decides whether that identity remains tied to an owner. Deposited into the clearing system, it joins the common stock and the depositing bank receives a balance; the bars a bank later withdraws need not be the ones it put in. Held as allocated metal, the same bar stays on one owner’s bar list under its own serial number, and an inspection can match the bar on the shelf to the line on the list.
What the system changes for a bank’s client
Since the trial began, a deal between two participating banks can settle in Hong Kong itself. Delivery versus payment is still to come. Once it is live, the risk of one side paying before the other delivers goes away.
Under a client’s account agreement with its bank, the client’s rights come from that contract and sit outside the Rulebook. State ownership of HKPMCC leaves the writing of those terms with the bank. The agreement also decides whether the client holds an account in ounces or specific bars.
If the agreement gives a position measured in ounces, the client’s gold is a claim on the bank. It carries the bank’s credit risk. Physical metal reaches the client only when the bank delivers bars against that claim. Specific bars come with a bar list that the holder can request and check against the bars themselves. Insolvency, audit and release treat the two arrangements differently.
Many holders keep both, one arrangement for liquidity and the other for metal they mean to hold. The new system serves the first. Gold a treasury expects to sell within the year might sit in a metal account at its bank, with the reserve its board has set aside placed in specific bars.
The documents that evidence title to specific bars
Title to specific bars is evidenced by a set of documents that follows the metal from sale to release.
| Document | What it shows |
|---|---|
| Commercial invoice on the actual bars | The sale names the bars it covers, by serial number and fine weight |
| Bar list | Every bar by serial number, refiner, fineness and fine weight |
| Allocation record | Which bars are held for this holder, and in which vault |
| Vault placement confirmation | The vault operator’s own confirmation that it holds those bars |
| Custody terms | Bars held separately from the custodian’s holdings and from gold belonging to other clients, never lent or pledged |
| Release terms | Who may instruct the vault, on what notice, and against what receipt |
The holder of these documents can report the metal as its own, have it counted bar by bar and call it out of the vault. Where a counterparty can produce only a figure in ounces, it is reporting a claim on itself. Audits start with the bar list, which the auditor takes into the vault to match serial numbers against the bars on the shelf. From the vault operator, the auditor can also obtain a holding certificate.
Allocated placement at Brink’s Hong Kong or Singapore
Golden Ark Reserve sells whole bars refined by Heraeus or Argor-Heraeus and, on the buyer’s written instruction, places them into allocated storage at Brink’s Hong Kong or Brink’s Singapore. The bars sit there in a dedicated client sub-account in which the buyer is named in the vault register. Allocated by serial number and segregated from the seller’s own stock and from other counterparties’ metal, they form no part of the vault operator’s assets. They are neither used nor pledged.
Once Brink’s takes possession against a receipt, each bar appears individually in the dedicated client sub-account. The commercial invoice is issued against the actual allocated bars. The buyer receives the Allocation Record and Brink’s placement confirmation, both part of the Evidence Set, together with a Confirmation of title to the bars. The buyer’s auditor can inspect the bars on prior written notice arranged through Golden Ark Reserve, verifying each recorded serial number. Storage carries a separate invoice. Unpaid storage invoices stay a debt that is never settled by selling the bars.
The holder starts a release by sending, two business days ahead, a written instruction that lists the bars and names the carrier or representative who will collect them. The instruction must match the registered list of authorised persons. The bars leave the vault in exchange for a written receipt. The holder then receives an updated Allocation Record. The storage contract with Brink’s remains with Golden Ark Reserve. If that arrangement ends, the bars move under their serial numbers to another vault or onward to the holder.
Commissioning in 2027 and the Singapore timetable
When the system is commissioned in the first quarter of 2027, the trial ends and Hong Kong has a standing route for settling gold between banks. The city’s first five-year plan, published in September 2026, names gold as the entry point to a wider commodity trading business and calls for one gateway to store, trade and clear it. A week earlier, the Financial Services and the Treasury Bureau and the Central Bank of Uzbekistan exchanged a memorandum of understanding on gold market cooperation, part of Hong Kong’s push to draw institutional bullion to its vaults.
If the Rulebook in force at commissioning differs from today’s, banks may update their client terms to match, which makes commissioning a date for their clients to re-read the account agreement.
Singapore is preparing a separate clearing system for Loco Singapore gold on a similar clock. Singapore Exchange is to have the over-the-counter system running by the end of 2026, in an initiative led by the Monetary Authority of Singapore and the Singapore Bullion Market Association. Interbank trading is expected to build from 2027, with six banks lined up as clearing members: DBS, Deutsche Bank, ICBC Standard Bank, J.P. Morgan, OCBC and UOB. Kilobars, the format Asian markets prefer, are to clear there alongside 400 oz bars, whereas Hong Kong’s system takes the larger bar alone.